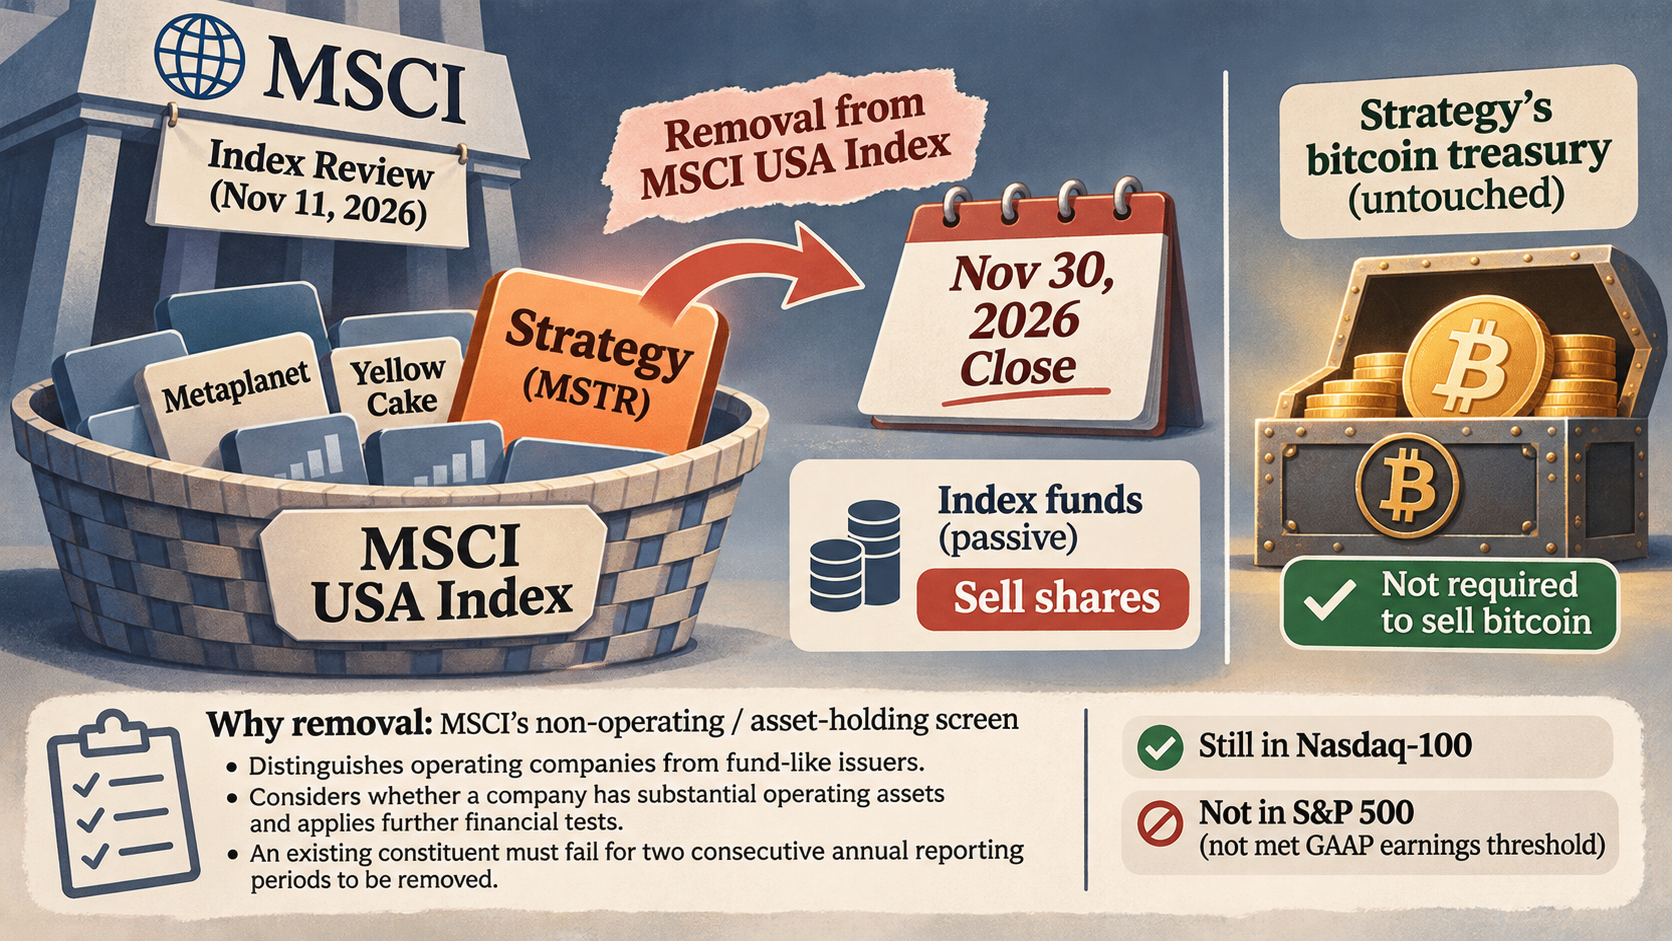
MSCI placed Strategy’s Class A shares on its removal list for the MSCI USA Index in its November 11, 2026, index review. The change was scheduled to take effect after the November 30 close. MSTR fell roughly 1.5%–2.6% at points in after-hours trading following the announcement.
As reported on November 12, 2026, the immediate question was how much index-tracking funds would need to sell. The removal does not require Strategy to sell any of its bitcoin.
Why MSCI removed the stock
MSCI’s previously adopted screen is designed to distinguish operating companies from fund-like issuers. It examines whether a company has substantial operating assets and applies further financial tests; an existing constituent must fail across two consecutive annual reporting periods before removal. Bitcoin accounted for more than 90% of Strategy’s assets, while its software business was small relative to its treasury holdings.
The broader removal discussion also included Japan’s Metaplanet and UK uranium holder Yellow Cake. That distinction matters: MSCI’s rule concerns the boundary between operating companies and asset-holding vehicles, rather than bitcoin alone. MSCI did not publish a company-by-company explanation of its screening decisions.
Strategy argued in its consultation response that the rule discriminated against digital-asset treasury companies. It said removal would not meaningfully affect its business. Its quarterly report, however, warned that losing index membership could weigh on its share price, liquidity and ability to raise capital.
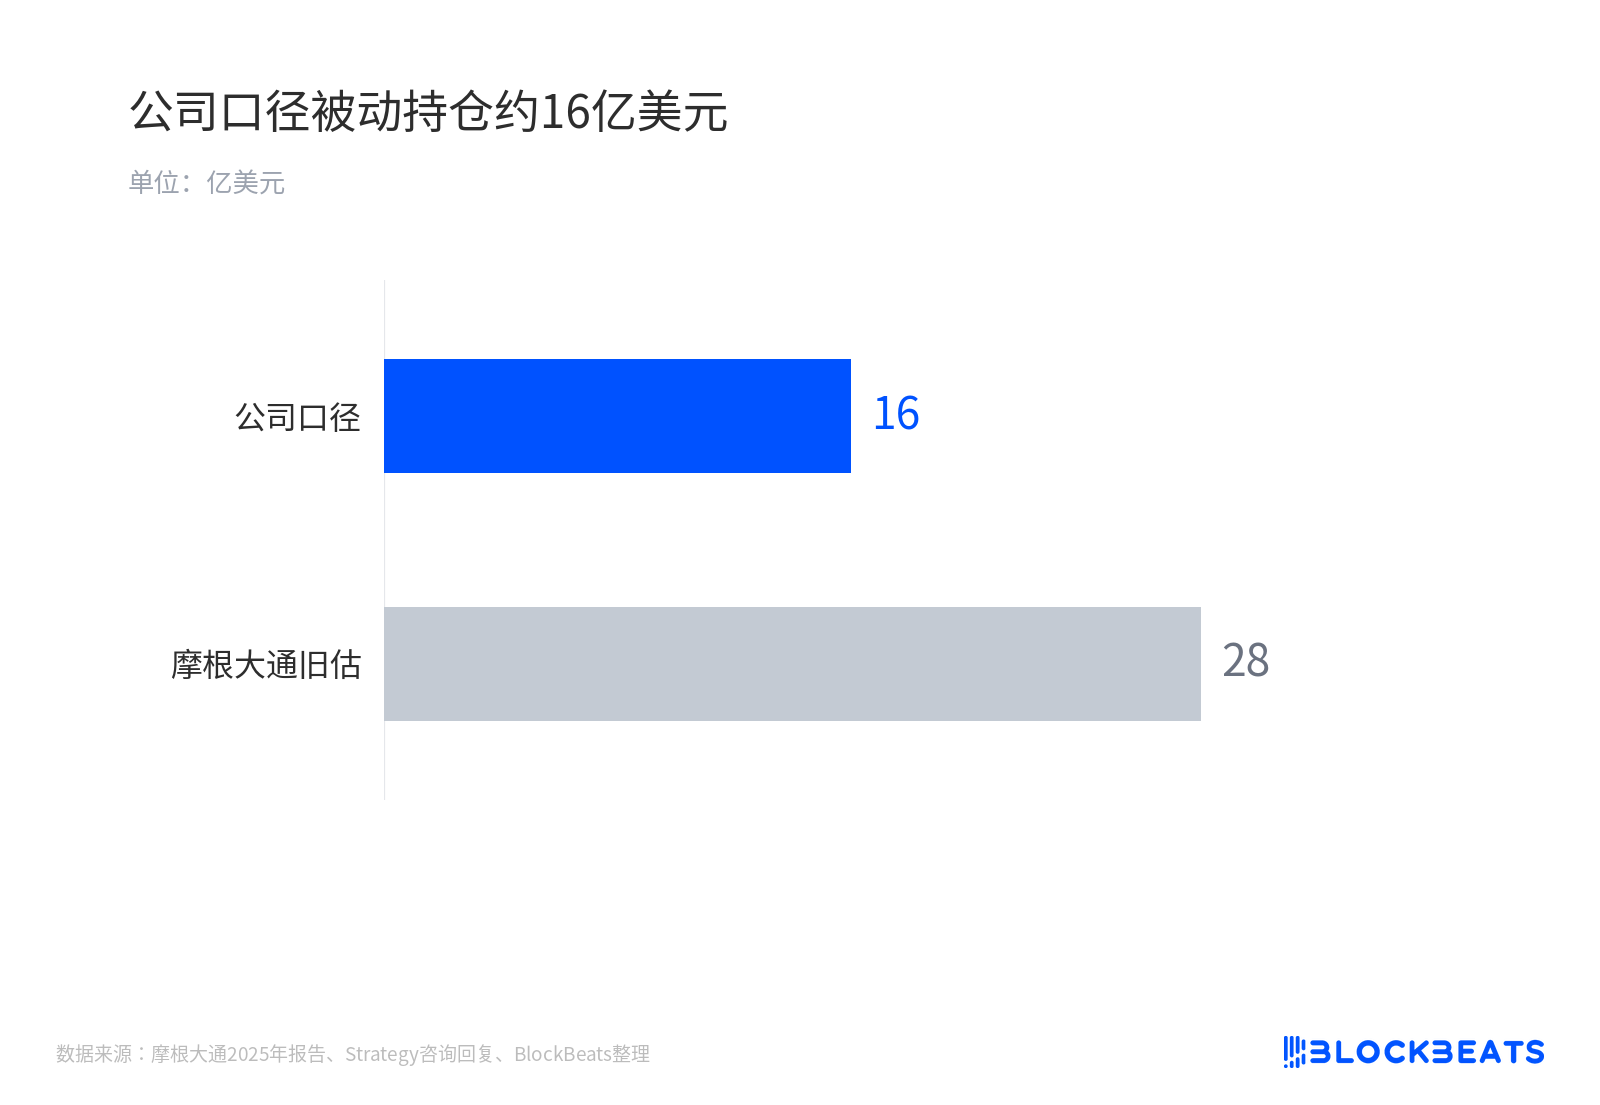
Two selling estimates, neither a confirmed outflow
A widely repeated $2.8 billion passive-selling estimate came from a November 2025 JPMorgan report by Nikolaos Panigirtzoglou’s team. It assessed an earlier proposal to exclude companies whose digital assets exceeded half their total assets. The report also estimated a further $8.8 billion if other index providers followed. Neither figure measures sales resulting from this review.
Strategy offered a different reference point in its consultation response: funds tracking MSCI global indexes held about 13 million shares, or 3.1% of its basic shares outstanding—less than one day’s trading volume, according to the company. At $122 per share, that holding was worth roughly $1.6 billion; the dollar conversion was a research calculation, not a figure supplied by Strategy.
Funds passively tracking the affected MSCI indexes faced a November 30 closing deadline to adjust their holdings. Active funds were not compelled to sell. As of the original report, MSTR remained in the Nasdaq-100; it had not entered the S&P 500 because it had not met that index’s GAAP earnings threshold. Neither S&P Dow Jones Indices nor FTSE Russell had publicly said it would follow MSCI.
The financing risk is separate from the index trade
At the time of reporting, Strategy held 850,364 bitcoin acquired for about $64.16 billion, at an average $75,456 per coin. With bitcoin near $74,000, the holding was below its average purchase price. The report put Strategy’s rough market-cap-to-bitcoin-holdings ratio at 0.82, without deducting debt.
That discount matters to Strategy’s share-issuance model: issuing stock below the value of the underlying holdings can dilute existing shareholders, making equity-funded bitcoin purchases less attractive. Index removal could reduce passive demand for the shares, but whether it would deepen the discount or constrain financing remained uncertain. The stock’s index-driven selling pressure should not be mistaken for a mandatory sale of bitcoin.